> ## Documentation Index
> Fetch the complete documentation index at: https://nixtlaverse.nixtla.io/llms.txt
> Use this file to discover all available pages before exploring further.
# Nonexchangeable conformal prediction
NexCP answers the same problem as [ACI](aci) — the world moved and the
calibration set is stale — from the opposite direction. Rather than
moving the coverage target, it changes whose errors count.
## What it does
Split conformal treats all `n` calibration windows as equally
informative, which is precisely the exchangeability assumption. NexCP
drops it and weights each window by its age:
```text theme={null}
w_i = rho ** (age of window i)
```
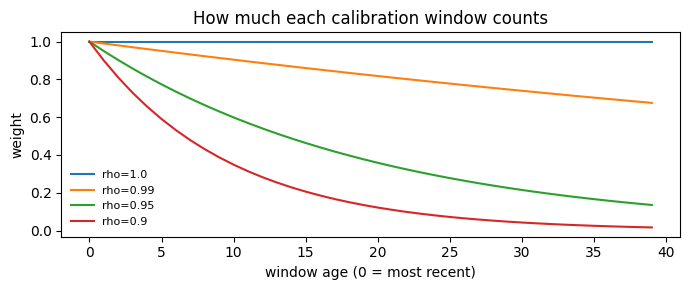
The newest window has weight `1`, the one before it `rho`, and so on.
The threshold is then the exact **weighted** order statistic of the
scores under those weights, not the unweighted one.
`rho` controls the memory. At `rho = 1` every weight is `1` and NexCP is
exactly split conformal. At `rho = 0.9` a window 20 steps back carries
12% of the newest window’s vote, and one 50 steps back is essentially
ignored.
Barber et al. give the price explicitly: the coverage gap is bounded by
the total variation between the weighted calibration distribution and
the test point’s. Down-weighting stale data shrinks that gap when the
process drifts, and costs you effective sample size when it does not.
> **The window axis has to mean time**
>
> NexCP reads axis 1 of the calibration arrays as chronological, oldest
> first. That is what `calibrate_cv` produces. If you assemble
> calibration windows yourself, get the order right or the decay is
> applied to the wrong windows silently.
## Worked example
This page uses the eight-series M4 hourly panel rather than
AirPassengers, because weighting only matters when the series are long
enough for old windows to genuinely be stale.
```python theme={null}
import matplotlib.pyplot as plt
import numpy as np
import pandas as pd
from statsforecast import StatsForecast
from statsforecast.models import SeasonalNaive
from conformalforecast import NonexchangeableConformalPrediction
from conformalforecast import panel as P
from conformalforecast.adapters import StatsForecastAdapter
from conformalforecast.diagnostics import evaluate, nexcp_state
HORIZON, SEASON, ALPHA = 24, 24, 0.1
N_HOLDOUT = 3
df = pd.read_csv("nbs/data/m4_hourly_panel.csv", parse_dates=["ds"])
matrix, index = P.long_to_panel(df["y"].to_numpy(), df["unique_id"].to_numpy(), df["ds"].to_numpy())
print("panel", matrix.shape, "series", index.series_ids)
# Hold the tail out before anything is fitted, so the coverage measured at the
# end of this page is measured on data no part of the pipeline has seen.
train_df = df[df["ds"] <= df["ds"].max() - pd.Timedelta(hours=N_HOLDOUT * HORIZON)].reset_index(
drop=True
)
print("training through", train_df["ds"].max(), f"({N_HOLDOUT * HORIZON} hours held out)")
sf = StatsForecast(models=[SeasonalNaive(season_length=SEASON)], freq="h", n_jobs=1)
sf.fit(train_df)
forecaster = StatsForecastAdapter(
sf=sf, train_df=train_df, horizon=HORIZON, freq="h", model_name="SeasonalNaive"
)
```
```text theme={null}
panel (8, 672) series ('H1', 'H10', 'H100', 'H150', 'H200', 'H300', 'H400', 'H50')
training through 2015-01-25 23:00:00 (72 hours held out)
```
> **`refit=True` for `SeasonalNaive`**
>
> `SeasonalNaive` has no `forward` method, so statsforecast cannot reuse
> fitted parameters across cutoffs and `calibrate_cv` must refit at each
> one. For this model that is free — there is nothing to fit.
```python theme={null}
N_WINDOWS = 40
RHOS = [1.0, 0.99, 0.95, 0.9]
fits, states = {}, {}
for rho in RHOS:
method = NonexchangeableConformalPrediction(alpha=ALPHA, rho=rho)
fits[rho] = method.calibrate_cv(forecaster, n_windows=N_WINDOWS, refit=True)
states[rho] = nexcp_state(fits[rho])
for rho, state in states.items():
label = "rho=1.0 (= split conformal)" if rho == 1.0 else f"rho={rho}"
print(
f"{label:28s} effective sample size {state['effective_sample_size']:6.2f}"
f" of {N_WINDOWS} windows"
)
```
```text theme={null}
rho=1.0 (= split conformal) effective sample size 40.00 of 40 windows
rho=0.99 effective sample size 39.47 of 40 windows
rho=0.95 effective sample size 30.12 of 40 windows
rho=0.9 effective sample size 18.45 of 40 windows
```
The effective sample size is what the decay costs. `rho = 0.99` is
almost free here — 39.5 of 40 windows — while `rho = 0.9` leaves the
equivalent of about 18. Fewer effective windows means a coarser quantile
grid and a noisier threshold. That is the trade: less stale information,
but also less information.
```python theme={null}
ages = np.arange(N_WINDOWS)
fig, ax = plt.subplots(figsize=(7, 3))
for i, rho in enumerate(RHOS):
ax.plot(ages, np.power(rho, ages), color=f"C{i}", lw=1.5, label=f"rho={rho}")
ax.set_xlabel("window age (0 = most recent)")
ax.set_ylabel("weight")
ax.set_title("How much each calibration window counts")
ax.legend(fontsize=8, frameon=False)
fig.tight_layout()
```
 ## What it does to the intervals
```python theme={null}
predictions = {rho: fits[rho].predict(matrix) for rho in RHOS}
series = 0
steps = np.arange(1, HORIZON + 1)
fig, ax = plt.subplots(figsize=(9, 3.8))
for i, rho in enumerate(RHOS):
interval = predictions[rho].interval[series, 0]
label = "rho=1.0 (split conformal)" if rho == 1.0 else f"rho={rho}"
ax.plot(steps, interval[:, 0], color=f"C{i}", lw=1.3, label=label)
ax.plot(steps, interval[:, 1], color=f"C{i}", lw=1.3)
ax.plot(steps, predictions[1.0].point[series, 0], color="k", lw=1.4, ls="--", label="forecast")
ax.set_xlabel("horizon (hours ahead)")
ax.set_ylabel(f"{index.series_ids[series]}")
ax.set_title("Faster decay, different band")
ax.legend(fontsize=8, frameon=False, ncol=2)
fig.tight_layout()
```
 ```python theme={null}
widths = {
rho: (predictions[rho].interval[..., 1] - predictions[rho].interval[..., 0]).mean(axis=(1, 2))
for rho in RHOS
}
header = "series " + "".join(f"{('rho=' + str(r)):>12s}" for r in RHOS)
print(header)
for s, name in enumerate(index.series_ids):
row = "".join(f"{widths[rho][s]:12.1f}" for rho in RHOS)
print(f"{name:9s}{row}")
```
```text theme={null}
series rho=1.0 rho=0.99 rho=0.95 rho=0.9
H1 140.0 146.7 155.0 165.3
H10 44.4 63.3 110.9 199.8
H100 539.5 610.9 666.8 811.3
H150 179.9 206.5 217.4 257.4
H200 0.4 0.4 0.4 0.4
H300 0.5 0.5 0.6 0.6
H400 89.3 93.8 133.2 205.0
H50 8804.0 8829.0 8829.8 9336.3
```
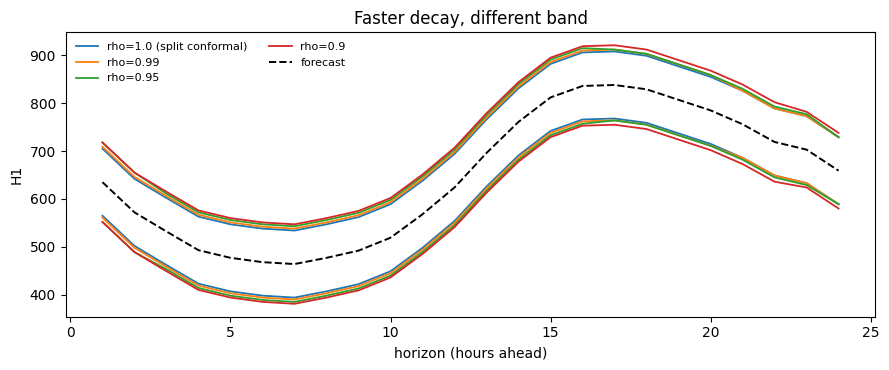
The widths move by series, not uniformly: `rho` reweights each series’
own residual history, so a series whose recent errors are unlike its old
ones changes a lot — `H10` more than quadruples between `rho = 1.0` and
`rho = 0.9` — while a stable one such as `H200` barely moves. A single
global multiplier could not do that.
## Measured coverage
```python theme={null}
histories, truths = [], []
for k in range(N_HOLDOUT):
end = matrix.shape[1] - (N_HOLDOUT - k) * HORIZON
histories.append(matrix[:, :end])
truths.append(matrix[:, end : end + HORIZON])
truths = np.stack(truths, axis=1)
for rho in RHOS:
report = evaluate(fits[rho], histories, truths)
label = "rho=1.0 (split)" if rho == 1.0 else f"rho={rho}"
print(
f"{label:18s} coverage {report.marginal_coverage:6.1%} "
f"width {report.mean_interval_width:9.1f} "
f"Winkler {report.mean_winkler_score:9.1f}"
)
```
```text theme={null}
rho=1.0 (split) coverage 85.9% width 1227.7 Winkler 1369.0
rho=0.99 coverage 89.4% width 1241.2 Winkler 1360.8
rho=0.95 coverage 92.5% width 1263.8 Winkler 1338.8
rho=0.9 coverage 94.8% width 1371.3 Winkler 1429.2
```
> **The decay pays for itself here, up to a point**
>
> Split conformal (`rho = 1.0`) under-covers on this holdout — 85.9%
> against a 90% target — because it weights a residual from 40 hours
> back exactly as heavily as the most recent one. Every decay setting
> closes that gap, `rho = 0.99` almost exactly (89.4%), and the Winkler
> score, which charges width and misses on one scale, improves with it,
> bottoming out at `rho = 0.95` (1338.8 against split’s 1369.0).
>
> Past that the trade turns over. `rho = 0.9` buys 94.8% coverage, well
> beyond what was asked for, and pays 12% more width than split
> conformal to get it; its Winkler score is the worst of the four. That
> is the shape to expect — forgetting stale residuals helps while they
> really are misleading, and costs you effective sample size once they
> are not. Measure before tuning `rho`, in both directions.
## When not to use it
* **Your calibration set is small.** Decay throws away effective
sample size you may not have. Check `effective_sample_size` against
`ceil(1/alpha)` before trusting the result.
* **Your drift is abrupt rather than gradual.** An exponential decay
is a smooth forgetting curve. A step change is handled better by
[ACI](aci), whose controller reacts to misses directly.
* **You do not know how fast to forget.** `rho` is as much a tuning
parameter as ACI’s `gamma`, and NexCP has no aggregated variant. If
that bothers you, use [AgACI](agaci).
## References
R. F. Barber, E. J. Candes, A. Ramdas, and R. J. Tibshirani, “Conformal
prediction beyond exchangeability,” arXiv.org, 2022.
[https://arxiv.org/abs/2202.13415](https://arxiv.org/abs/2202.13415).
## Next
* [SPCI](spci) — the last online method, and the only one that changes
the shape of the band rather than its level.
* [Ragged panels](../capabilities/ragged-panels) — what the window
axis means when series have different lengths, which is exactly what
NexCP reads.
## Related topics
- [Methods](/conformalforecast/methods.html.md)
- [conformalforecast](/conformalforecast/index.html.md)
- [Architecture](/conformalforecast/docs/concepts/architecture.html.md)
- [Conformal Prediction](/statsforecast/docs/tutorials/conformalprediction.html.md)